
With a Part 1045 rollover, founders can salvage QSBS earlier than 5 years – TechCrunch
The tax code incorporates provisions that encourage investments within the expertise startup ecosystem and small companies by rewarding founders, VCs and buyers for taking excessive ranges of threat in founding or investing in a startup. Certainly one of these provisions is the Certified Small Enterprise Inventory (QSBS) or Part 1202 inventory, which affords the chance to get rid of capital positive aspects tax completely if particular necessities are met.
You will need to observe that this 100% capital positive aspects exclusion, made everlasting by the Obama administration, has been included within the draft laws by the Home Methods and Means Committee, and features a proposed lower from 100% exclusion to a 50% exclusion for positive aspects acknowledged on the sale of QSBS. For the aim of this text, I’ll communicate particularly to the 100% exclusion.
You’ll be able to study extra concerning the QSBS guidelines and necessities right here. One rule we focus on right this moment is that stockholders should meet a five-year holding interval to qualify. Nevertheless, not everybody can time when to promote their firm. The truth that many acquisitions occur earlier than 5 years leaves some founders and buyers wanting qualifying for these highly effective tax financial savings.
Stockholders can multiply — or “stack” — the advantage of a 1045 rollover by spreading the QSBS exclusion to multiple new funding.
Part 1045 can salvage the chance in some instances.
What’s Part 1045?
Part 1045 permits a founder or stockholder whose firm has been bought earlier than the five-year holding interval to defer the capital positive aspects by rolling the sale proceeds right into a substitute QSBS.
Advantages and alternatives
A 1045 rollover allows founders and buyers to benefit from a number of tax advantages and alternatives they might in any other case miss.
Prolonged tax deferral
With a 1045 rollover, the stockholder can defer taxes on the sale of the unique QSBS by investing in a substitute QSBS. Underneath the appropriate circumstances, tax may be deferred till the substitute QSBS is bought.
If the mixed holding interval is 5 years and different necessities (mentioned beneath) are met, no federal capital positive aspects taxes are due. But when the necessities are usually not met, then taxes can be due upon the sale of the substitute QSBS.
Shortened holding interval
Usually, the holding interval for all taxable exchanges will start the day after the change. Nevertheless, the holding interval for the substitute QSBS consists of the holding interval of the unique QSBS, avoiding a reset of the five-year requirement. This implies a 1045 rollover shortens the following QSBS holding interval requirement and permits the clock to proceed ticking.
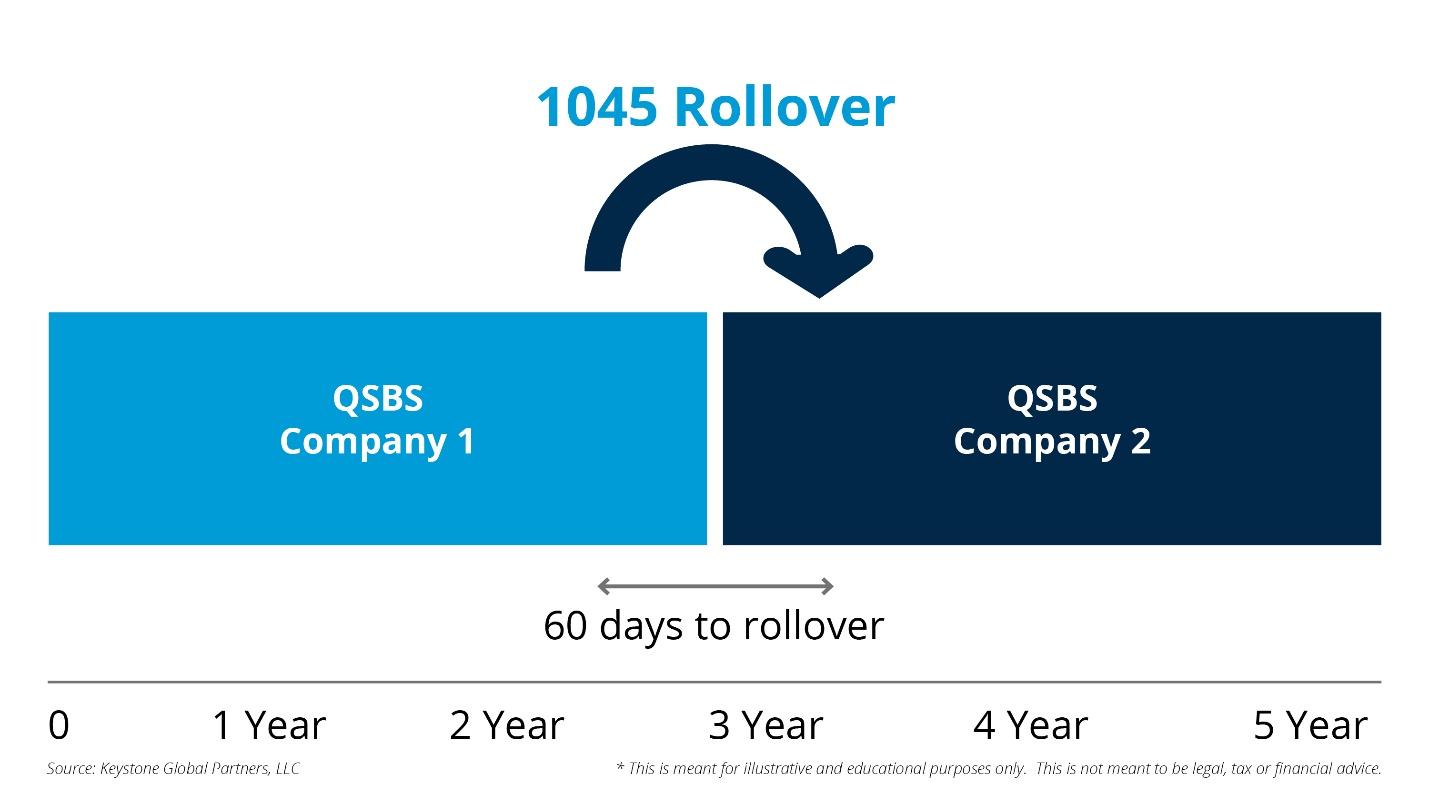
1045 Rollover. Picture Credit: Keystone International Companions