
Ventures Platform, Hustle Fund again Nigerian fintech Brass in $1.7M spherical – TechCrunch
Small and medium enterprises make up greater than 95% of all companies in Nigeria. However regardless of their sheer measurement and significance, a majority of them are underserved by monetary establishments and lack the total suite of monetary providers wanted to scale their operations.
Except for full-stack monetary wants, together with credit score, small and medium companies require different important assets to know their monetary operations.
Brass is a Nigerian fintech tackling these challenges by offering banking providers to small and medium companies. The corporate has secured a $1.7 million funding spherical to scale its choices for “native entrepreneurs, merchants and fast-growing companies.”
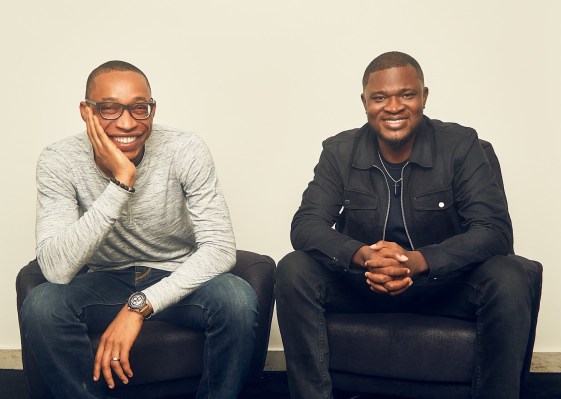
Sola Akindolu and Emmanuel Okeke based Brass in July 2020. Earlier than Brass, CEO Akindolu was the top of product at YC-backed Kudi, whereas CTO Okeke was an engineering supervisor at Stripe subsidiary Paystack.
Akindolu’s work at Kudi opened his eyes to the issues small and medium companies face in Nigeria. He defined that he discovered how onerous it was for these companies to have seamless monetary operations and cash-flow assist providers integral to monitoring vendor funds, cash motion and general enterprise well being.
However why begin Brass when there are present merchandise within the Nigerian market that SMEs and entrepreneurs can use? Sparkle, as an example, gives each private and enterprise banking providers (with extra precedence on the latter). Shopper neobanks Carbon and Kuda are in various phases of providing enterprise options to SMEs. Prospa, a YC-backed firm that doesn’t like to think about itself as a neobank, additionally offers software program and banking providers to microbusinesses and freelancers.
Akindolu believes that whereas these merchandise have their entry factors into the SME market, they don’t seize your complete banking wants of companies like Brass.
“There are lots of methods cash can get out of the enterprise, be it payroll, vendor cost, invoicing. We wish to assist companies’ money circulate; we wish to assist them in these areas to make it possible for cash retains working and so they can continue to grow their enterprise,” Akindolu mentioned, describing Brass’ software. “In order that’s, for essentially the most half, what we’re doing with Brass at present: monetary operations and money circulate assist.”
Brass gives a collection of merchandise — credit score and cost providers, payroll and expense administration, API assist, cash-flow analytics, group and speak to administration, different core enterprise providers resembling POS, debit and bank cards — all wrapped round a enterprise checking account.
Of all these options, Brass is betting huge on credit score with Brass Capital, an area already heating up with different platforms resembling Float, which offers working capital and software program providers to companies. That mentioned, Brass Capital has completed fairly nicely in a brief period of time; the cash-flow financing service claims to have disbursed greater than $2 million in credit score after getting used for six months by two dozen Brass prospects in personal beta.
Akindolu instructed TechCrunch that the corporate would make the service out there to the general public quickly.
Brass says that lots of its shoppers use the platform as their default money-operation service supplier. The fintech makes cash from offering credit score and API calls on its common product providing, mentioned the CEO.
It has over 5,000 prospects starting from colleges and malls to eating places and fintechs resembling Eden and Mono, which use its full banking answer. And unlike different platforms, Brass is making an attempt to optimize its platform for various ranges of companies with various wants on the identical time.
“What we’ve got down to do is to construct stacks of monetary operation providers. We could also be overkill for a micro enterprise; they may not discover us helpful, so we’re extra involved about small and medium-sized companies.”
The mission to make banking work for small companies was one motive why pan-African VC agency Ventures Platform invested within the firm, in keeping with its founder and common associate, Kola Aina.
Different buyers embody Flutterwave CEO Olugbenga “GB” Agboola, Paystack co-founder Ezra Olubi, Hustle Fund, Acuity Ventures and Uncovered Fund.
Earlier backers embody Olumide Soyombo of Voltron Capital, Leonard Stiegler and Fola Olatunji-David.
“We are excited to again Sola and the Brass group, who’re offering essential monetary know-how to Africa’s companies, beginning with Nigeria’s roughly 41.5 million companies,” mentioned Elizabeth Yin, the final associate at Hustle Fund.
It’s not simply in Nigeria that entry to complete banking options providers continues to be one of the vital important constraints for SMEs — it’s most main economies in Africa. Certainly, the continent’s formal SME sector has an annual financing hole of over $136 billion, though they account for over 80% of employed folks.
Because of this, Akindolu affirmed that Brass would use a part of the financing to take its enterprise to Kenya and South Africa by subsequent 12 months (it has finalized incorporation within the former). Integral to driving its growth plans throughout Africa is a partnership with Flutterwave, the one-year-old firm mentioned in a press release. Brass additionally plans to diversify its buyer base by launching extra product classes, particularly round credit score in its markets.