

S&P 500 Earnings: Ahead Estimates – ‘Inflation vs. Marketplace for recession danger
mixmotive / iStock Editorial through Getty Photos
It looks like we’re preventing the legendary nine-head hydra, however with three heads, one in every of which is inflation, two is recession, and the third is “how lengthy can the S&P 500 earnings estimates maintain?”
With Might ’22 jobs rely this morning, it appears nearly nobody talked about that “common hourly wage” got here in at + 0.3% in opposition to anticipated + 0.4%.
It’s unlikely that power (ie crude oil) or meals value pressures will quit instantly, however the expectation is that the opposite parts will start to weaken step by step (no less than the Fed governors will preserve telling us that). The Might CPI might be launched on Friday 10 June earlier than the opening clock, and the general CPI is anticipated to be +0.7%, whereas the core CPI is anticipated to enter +0.5%, a lower from the earlier +0.6 %. Subsequent week, June 15, is the subsequent FOMC assembly, and the anticipated daring funds enhance by 50 bps to the vary of 1.50%.
The three,800 degree held on the S&P 500 (the truth is, 3,810 was the bottom on Might 20), which is a very powerful 1/3. retracement degree for the S&P 500 in response to most of the good technicians.
The cautious feedback about Apple (AAPL) at this time by Katy Huberty of Morgan Stanley despatched the inventory down -3.8%, however it couldn’t even attain the typical quantity. Right here’s a fast have a look at Apple’s upcoming EPS and income estimates revisions:
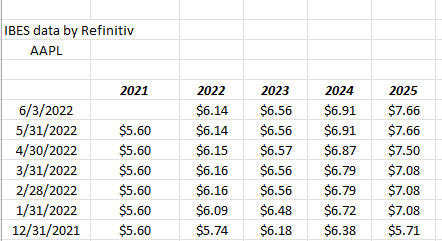
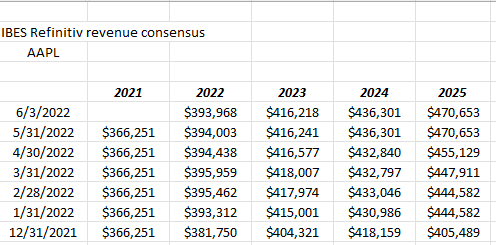
Observe the revisions from 2022 onwards: nonetheless trying okay. Among the different FAANG members look far, far worse. Not a lot injury right here, although (but).
S&P 500 knowledge from TWIE and the earnings scorecard: (IBES knowledge from Refinitiv)
- The 4-quarter ahead estimate jumped again to $ 235.17 this week from final week’s $ 233.49.
- The PE ratio on the ahead estimate was 17.5x in opposition to final week’s 17.8x;
- The S&P 500 earnings return rose to five.72% this week from 5.62% final week;

Right here’s part of the earnings spreadsheet (see the spreadsheet above this sentence) that doesn’t present an excessive amount of: these are the annual S&P 500 EPS estimates with the quarterly bottom-up estimates.
Take a look at Q1 ’22: since April 1, ’22 or the close to begin of Q1 22 earnings, the bottom-up quarterly estimate has risen 6.5%, which is the conventional or larger finish of the everyday “shock” issue. Q2 ’22 has not moved in any respect. And it normally occurs solely after July 1, ’22.
We (readers / traders) are returning to the conventional typical sample of S&P 500 earnings estimates, and will probably be extra after the Q2 ’22 outcomes have come, as will probably be the final quarter of tough Covid distortion we are going to see. In Q2 ’21, the S&P 500 EPS grew 96%, whereas the S&P 500 income grew 25%. Uncertain, we’ll see it evaluate for some time.
See credit score spreads: Credit score danger rose sharply final week, together with the S&P 500’s rise of 6%. This 12 months, it has been troublesome to find out how massive part of the worth decline has been duration-related, and the way a lot credit score deterioration has been anticipated in high-yield company bonds and high-quality bonds. With econ knowledge holding and S&P 500 earnings holding, you need to assume that a lot of the worth decline on these automobiles was rate of interest associated. LQD and Bloomberg’s investments for company bonds with funding ratios began in 2022 with durations of over 9%. It was troublesome to personal that asset class for patrons, and we didn’t and took credit score danger within the short-term high-yield bond ETF SHYG and Nuveen’s municipal high-yield and short-term high-yield funds, however offered all of them in early April ’22.
In 2007 and 2008, rates of interest have been falling, however credit score spreads widened. In 2022, rates of interest will rise and credit score spreads may also widen.
Neither LQD, AGG nor Pimco’s BOND fund ETFs have been capable of get better their downward 50-day transferring common. They jumped proper from final week the place the typical acted as resistance.
Prime 12 shares per 31/5/22:
- Schwab cash market fund
- Blackrock Strategic Inc Fund: -3.70% YTD
- S&P 500 Equal Weight ETF (RSP): -8.11% YTD Yield
- JP Morgan Earnings Fund: -4.62% YTD Yield
- Microsoft (MSFT): -18.79% YTD return
- Oakmark Worldwide: -9.90% YTD return
- Charles Schwab (SCHW): -16.17% YTD return
- Tesla (TSLA): -28.25% YTD return
- JPMorgan (JPM): -15.23% YTD Yield
- Merck (MRK): +21% YTD return
- Pfizer (PFE): -8.82% YTD Yield
- Amazon (AMZN): -28% YTD return
Pr. On Might 31, the SPY was down -12.79% and the AGG was decrease -8.74%. A 60% S&P 500/40% AGG balanced benchmark portfolio was decrease YTD by -11.17%.
Abstract / conclusion: There isn’t a doubt that the vary of outcomes for varied asset class returns for retail traders has elevated dramatically in 2022, however with the Fed / FOMC two consecutive 50 bps Fed funds fee hikes on June 15 after which once more in July, prospects have been sitting on more money than typical. Because the recession danger grew, shoppers have been informed they’d seemingly see extra positions performing higher below financial constraint, with these ETFs or funds or securities added after every fee hike.
By way of how lengthy the S&P 500 earnings will final, Apple at this time was an important instance of what a downgrade can do for a inventory in a tough band. EPS and earnings estimates are nonetheless seeing optimistic critiques, and but the inventory is up 16% from its file excessive of $ 180.
There are few locations to cover on this market the place the greenback (UUP) is one, gold is flat to 2% larger in 2022, after which money / cash markets.
It has been troublesome to diversify accounts for shoppers in 2022: When 2022 began, consumer accounts had 10% – 12% in both Oakmark Worldwide Fund or EMXC (rising markets ex-China ETF), and each are adverse YTD, with Oakmark Int ‘l primarily due to Ukraine and its influence on Europe and EMXC due to China’s issues with different rising markets.
The worth funds have even fallen in comparison with the 12 months. Invoice Nygren at Oakmark is a big worth investor, and per. 31/5/22 his fund had fallen -8.5% in 2022.
None of it is a advice or a suggestion for buy or sale. Buyer holdings can change shortly and previous outcomes are not any assure of future outcomes. Capital market situations can change quickly. Do your individual homework, and assess your individual willingness to take dangers in relation to volatility within the capital market.
Personally, I don’t suppose it is a repetition of 2001 – 2002 or 2007 – 2008, however the next occasions could be worrying both collectively or individually:
1.) The ten-year authorities rate of interest is traded up by 3.16%, Might 9 excessive rate of interest print;
2.) Crude oil trades up by the $ 130- $ 131 excessive from early March ’22;
3.) The S&P 500 trades and closes under 3,800 at excessive quantity.
Thanks for studying.
Unique submit
Editor’s word: The abstract factors for this text have been chosen by the Searching for Alpha editors.