
Goodly, centered on pupil mortgage compensation as an worker profit, finds tailwinds – TechCrunch
Goodly, a three-year-old, San Francisco-based startup, has been steadily constructing its enterprise with a five-person group and never a lot funding — $1.5 million secured in 2019 and, extra just lately, an undisclosed quantity of funding from Beth Axelrod, a longtime HR exec and the worldwide head of worker expertise at Airbnb.
The startup, which goals to make it lifeless easy for firms to supply tax-free pupil mortgage compensation as an worker profit, is worthwhile. It has unique relationships with quite a few brokers, together with insurer NFP and the a lot bigger Willis Towers Watson. Nonetheless, its product wasn’t precisely prime of thoughts through the pandemic, when enterprises grew to become consumed with distant work and attempting to make sure their workers’ psychological well-being.
Crusing into 2022, that may very well be altering for 2 causes. One ties to a provision throughout the Consolidated Appropriations Act of 2021 that enables employers to contribute as much as an annual most of $5,250 per worker to repay pupil debt. These contributions from the corporate are tax deductible for employers but additionally are excluded from taxable earnings for workers, which is able to seemingly give firms a a lot bigger monetary incentive to offer them.
Second, after greater than 20 months of non permanent pupil mortgage forbearance for hundreds of thousands of pupil mortgage debtors, pupil mortgage reduction is ending on January 31, which implies that starting in February, federal mortgage funds will resume with their regular (and usually onerous) rates of interest. Which means a difficulty that has been shelved for a while will all of a sudden leap to the forefront, and in a aggressive job market, firms would most likely be sensible to take word.
Definitely, Goodly CEO Gregory Poulin — who was among the many earliest workers at Parker Conrad’s Rippling, together with co-founder and CTO Hemant Verma — has a compelling pitch ought to they determine to research additional. As Poulin instructed us earlier this week, whereas $5,250 might not seem to be a lot, it could actually add up in stunning methods over time.
“For the common firm that we work with, we often see round $100 per participant per 30 days being the most typical contribution,” he says, evaluating the fee to a cup of espresso per day. However taking that employer contribution and making use of it as a cost on to the principal of pupil mortgage additionally helps handle the difficulty of compounding curiosity over the lifetime of the mortgage, which is the place folks actually get into hassle.
Poulin says the standard compensation interval is about 10 years and that Goodly can cut back that compensation interval by three to 4 years relying on the excellent stability of an worker’s mortgage. That doesn’t sq. precisely with the information that we’re seeing and which reveals that compensation intervals truly common nearer to twenty years, however clearly if Goodly will help somebody save even a yr of mortgage funds, that’s one thing employers can use as a sweetener.
For what it’s value, the startup’s tech is pretty easy. Every person of Goodly is given their very own account, the place they will handle and observe their pupil loans from its dashboard. From there, workers may entry content material like monetary wellness counseling, or the very best methods for optimizing repayments.
Poulin provides that one particularly widespread characteristic is the power for workers to ask their mates or household to make a contribution towards their pupil loans that capabilities in an identical solution to crowdfunding, whereby a father or mother or grandparent could make a one-time or a recurring contribution. “And naturally, that contributor has peace of thoughts in understanding that cost is being directed to that pupil mortgage and never spent on anything,” he says.
Goodly handed via Y Combinator shortly after its launch in 2018. Poulin says he was impressed to launch the enterprise after the sudden dying of his personal father whereas he was a pupil at Dartmouth, after which he discovered himself having to borrow $80,000 in pupil loans.
Years later, he says his cost continues to be greater than $900 a month.
He has numerous firm, sadly. As of final yr, there have been 45 million debtors who collectively owed practically $1.6 trillion in pupil mortgage debt within the U.S., and for too lots of them, it could actually develop into crushing. “It actually creates a two-tiered office the place these with pupil loans are in numerous methods, second-class residents,” says Poulin, “as a result of by the age of 30, folks with pupil debt maintain about half the retirement financial savings of their friends with out pupil loans,” inflicting them to delay homeownership, getting married and having youngsters.
If Goodly has its means, when pupil debt regains mindshare in 2022, extra employers will start to acknowledge the difficulty — and do extra to assist their workers mitigate the cycle.
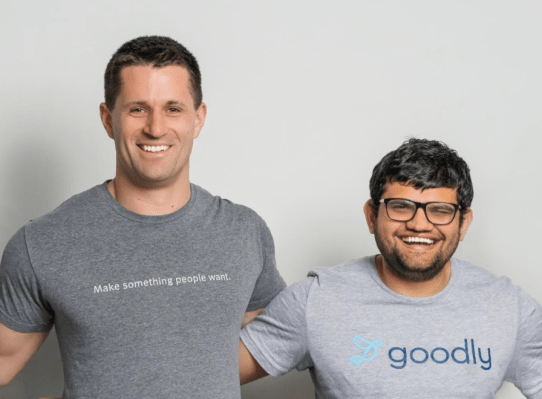
Pictured above, left to proper: CEO Gregory Poulin and his co-founder and Goodly’s CTO, Hemant Verma.