

Goldman Sachs explains why you need to ‘purchase’ these 2 cybersecurity shares
Our digital world runs on pc tech, and that tech is simply going to turn out to be extra autonomous and extra ubiquitous. And that, in flip, solely underscores the continued significance of on-line safety. With digital automation rising, it’s extra vital than ever, proper now, to begin firming up the digital protections.
In opposition to this backdrop, Goldman Sachs’ Gabriela Borges has turned her eye on the cybersecurity sector. The analyst sees a number of {industry} dynamics which might be favorable for long-term buyers, together with: “(1) Multi-product platforms have gained momentum and are nearer to fixing the problem of staying revolutionary in subsegments traditionally outlined by increase and bust product cycles. (2) The {industry} is much less cyclical as combine shifts away from {hardware} and towards SaaS, and given constant prioritization of safety spend in enterprise budgets.”
Borges doesn’t depart us with a macro view of the {industry}. The analyst goes on to offer a drill-down to the micro stage, and picks out two cybersecurity shares that she sees as potential winners for the lengthy haul.
In actual fact, Borges isn’t the one one singing these shares’ praises. In accordance with the TipRanks platform, every boasts a “Robust Purchase” consensus ranking from the broader analyst group, and presents double-digit upside potential for the yr forward. Let’s take a more in-depth look.
CrowdStrike Holdings (CRWD)
The primary Goldman-pick we’ll take a look at is CrowdStrike, the producer of the high-end Falcon Endpoint Safety line, and a frontrunner within the cybersecurity ecosystem. CrowdStrike’s merchandise have set an {industry} commonplace for on-line community safety and for digital safety, and embody a variety of cloud-based modules for all kinds of functions. The corporate makes the merchandise accessible by subscription by way of the Software program-as-a-Service mannequin.
The corporate reported some sound metrics in its final quarterly report, for Q3 of fiscal 2023. Income was up 53% year-over-year, at $581 million, and annual recurring income, at $2.34 billion, was up 54%. On the underside line, CrowdStrike reported a fiscal Q3 earnings of 40 cents per share, by non-GAAP measures, beating consensus estimate of 32 cents per share.
Nevertheless, the corporate supplied income steering that fell wanting estimates. Particularly, This fall income is predicted to be in a variety of $619.1 million to $628.2 million, beneath Avenue estimates of $634.2 million.
Whereas acknowledging that present market situations act as a headwind on the inventory, Goldman Sachs’ Gabriela Borges believes it’s well-placed for sturdy progress.
“We anticipate to see a moderation in progress fee… pushed primarily by slower progress within the endpoint TAM and a slower tempo of market share acquire – and we consider that is properly understood by the market. Over the medium time period, 1) we anticipate to see regular progress in endpoint (80%+ of ARR), based mostly on our bottom-up market share mannequin suggesting next-gen endpoint applied sciences maintain near 50% share at present; 2) we anticipate to see outsized progress in cloud, the place our {industry} conversations recommend CrowdStrike is aggressive given its core competencies in information assortment and monitoring,” Borges opined.
“Taken along with sturdy FCF technology at present and a reset to numbers in 3Q23 (2023 Avenue income has been revised down 3% during the last 3 months), we consider threat/reward is engaging,” the analyst summed up.
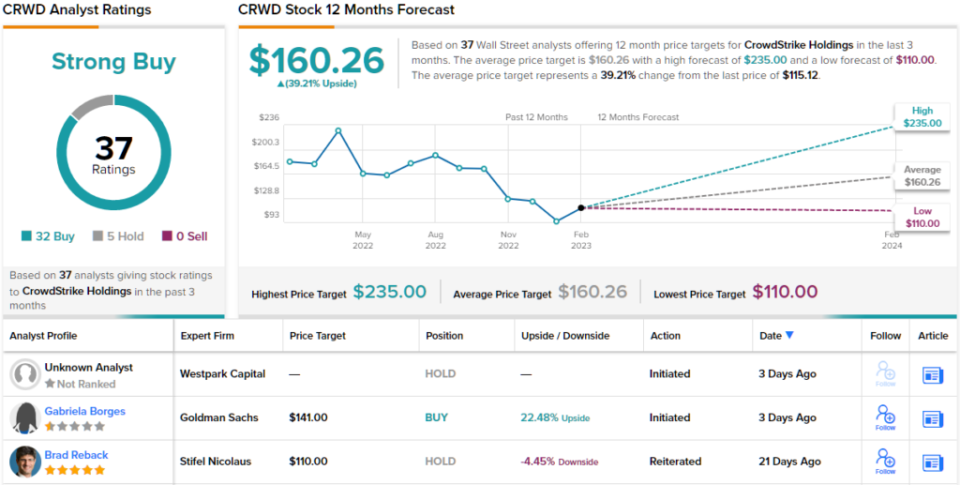
Total, Borges believes it is a inventory value holding on to. The analyst charges CRWD shares a Purchase, and her $141 value goal suggests a 22% upside within the subsequent 12 months. (To observe Borges’ observe file, click on right here)
Altogether, CrowdStrike has 37 current analyst critiques on file – these embody 32 Buys and simply 5 Holds, for a Robust Purchase consensus ranking. The shares are promoting for $115.12 and the typical value goal, now at $160.26, implies a 39% one-year acquire. (See CRWD inventory forecast)
Palo Alto Networks (PANW)
The subsequent inventory on Goldman’s radar is Palo Alto Networks, one other main title in digital safety. This firm’s mixture of firewall merchandise and state-of-the-art cybertech presents clients a excessive stage of safety for on-line programs, together with safety in opposition to malware assaults, and likewise permits automation of community and on-line safety operations. Palo Alto additionally makes its enterprise-grade safety software program accessible to residence and small enterprise customers trying to shield their community and cloud functions.
Over the previous couple of years, Palo Alto has constructed a steadily rising income stream based mostly on its product line and industry-leading status. Within the final reported quarter, for fiscal 1Q23, the corporate reported $1.56 billion on the high line, based mostly on $175 billion in complete billings. These figures represented year-over-year will increase of 25% and 27% respectively. The corporate’s backlog, a key indicator of future work and revenues stood at $8.3 billion as of October 31 final yr.
On the backside line, Palo Alto posted an adjusted 83 cents per share, beating estimates of 69 cents per share. The corporate completed its fiscal first quarter with a $1.2 billion in free money circulate, and almost $2.1 billion in money readily available. We’ll see subsequent week, when Palo Alto stories earnings for fiscal Q2, how its efficiency is holding up.
Within the meantime, Goldman’s Borges sees a transparent path ahead for the corporate, and lays it out in simple prose: “We view Palo Alto as a portfolio of community, endpoint and cloud merchandise at completely different levels of product maturity, every leveraging centralized area experience in person interface/person expertise (UIUX), advertising and marketing, safety intelligence and machine studying. Along with a profitable M&A method, we anticipate to see sturdy progress of ~20% for the subsequent 5 years with high quartile software program KPIs, a path to GAAP profitability this yr, and energetic capital allocation.”
Monitoring forward from right here, Borges provides PANW shares a Purchase ranking, with a $205 one-year value goal that implies a possible acquire of 19%.
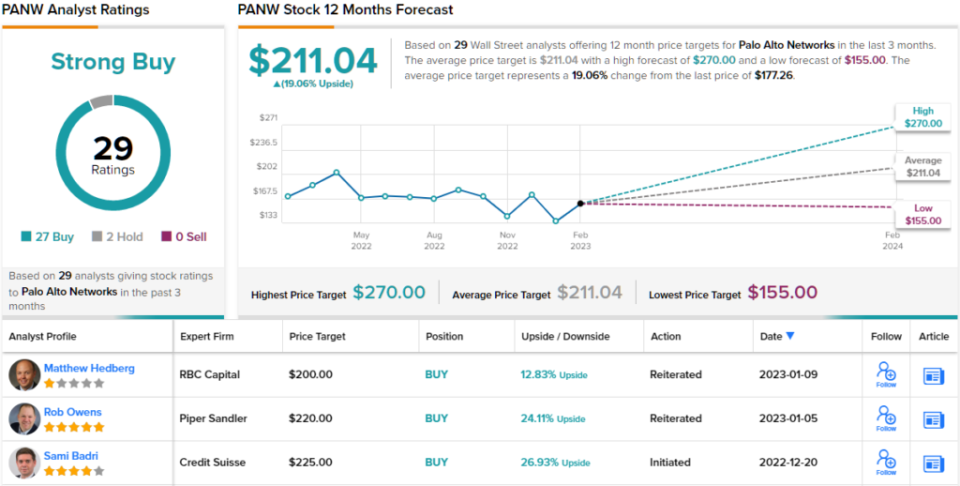
The Robust Purchase consensus ranking on this inventory exhibits that the Avenue is clearly in-line with Goldman’s bullish view; of the 29 current analyst critiques, 27 are to Purchase and solely 2 to Maintain. PANW shares have a mean value goal of $211.04, implying a 19% upside from the buying and selling value of $172.02. (See PANW inventory forecast)
To seek out good concepts for shares buying and selling at engaging valuations, go to TipRanks’ Greatest Shares to Purchase, a device that unites all of TipRanks’ fairness insights.
Disclaimer: The opinions expressed on this article are solely these of the featured analysts. The content material is meant for use for informational functions solely. It is vitally vital to do your individual evaluation earlier than making any funding.