
Financial institution prices fall on digitisation and better curiosity earnings
Capital Markets
Financial institution prices fall on digitisation and better curiosity earnings
Monday September 26 2022

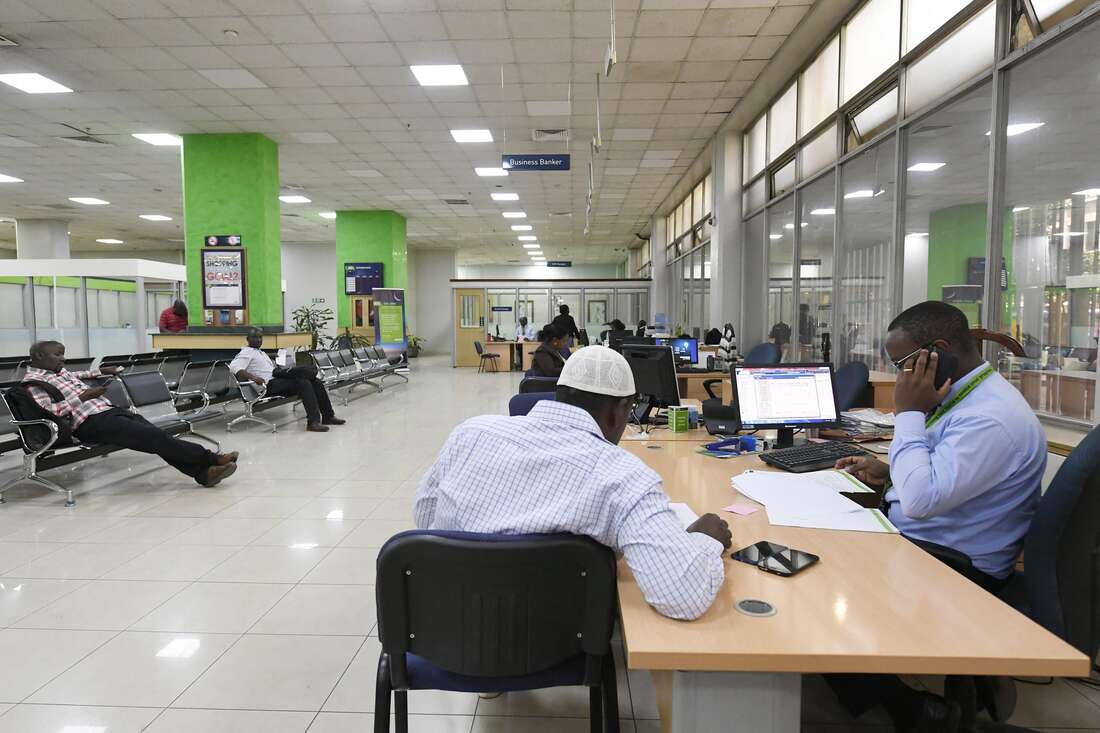
A buyer is served on the Kenya Industrial Financial institution (KCB) in Nairobi on January 24, 2018. PHOTO | SIMON MAINA | AFP
Listed banks improved their effectivity within the first half of the yr after holding a lid on prices whereas having fun with greater income in a recovering financial system that supported greater lending and price earnings.
Within the first half of the yr, seven of the ten native listed banks minimize their cost-to-income ratios—the exceptions being KCB, Customary Chartered Kenya and DTB— that means they had been successfully spending much less to generate each shilling of earnings.
Evaluation carried out by Dyer & Blair Funding financial institution reveals that the typical ratio for the ten lenders within the six months to June 2022 was 50.15 %, in comparison with 54.2 % within the first half of 2021.
Lenders have been leveraging on digitisation to chop overheads, and on the identical time improve their non-funded earnings by way of the charges that use of those different banking channels generate.
Curiosity earnings additionally rose according to greater lending volumes—with annualised development in credit score to the non-public sector rising from 8.6 % on the finish of 2021 to 12.2 % in June.
It went up additional to a six-and-a-half yr excessive of 14.2 % in July, earlier than retreating to 12.5 % in August on account of companies exercising warning through the Basic Elections interval.
“The sector-wide enchancment in effectivity was primarily bolstered by complete working earnings rising at a quicker tempo than working prices (excluding provisions),” mentioned Dyer & Blair.
“This enchancment factors to the truth that banks are more and more persevering with to leverage their different banking channels to each enhance non-funded earnings and cut back prices.”
Dyer & Blair nevertheless famous that lenders which have focused on bettering the standard of their property (mortgage books) have suffered on the price facet—the place a fall in non-performing mortgage ratios has been matched with a better cost-to-income ratio.
“While each asset high quality and effectivity ranges are influenced by various components, we imagine that the aforementioned relationship paints an image of how asset high quality enchancment is partly decided by financial institution initiatives – which might show expensive,” mentioned the funding financial institution.
[email protected]
Associated