
Closely VC-backed salad chain Sweetgreen heads towards public markets – TechCrunch
Hire the Runway is anticipated to cost its IPO later immediately and commerce tomorrow morning, offered that each one issues go as deliberate. Udemy can be on the best way to the general public markets. Allbirds, too.
And this week, Sweetgreen threw its hat into the ring.
Sweetgreen is a meals chain greatest identified for salads which are in style with the office-lunching crew. I can safely say that as a longtime member of that cohort again once I labored in an workplace in a serious metropolis.
Why are we speaking a couple of fast-casual restaurant chain right here on TechCrunch? As a result of Sweetgreen raised a whole bunch of thousands and thousands of {dollars} throughout its life as a non-public firm, together with myriad enterprise capital rounds — by means of a Sequence I in 2019 — together with capital from different buyers.
It’s an extremely well-backed unicorn, in different phrases. It simply occurs to make salads as an alternative of, say, enterprise software program.
So, let’s take a dive into its IPO submitting, working to each perceive the corporate’s enterprise and its outcomes. We’ll shut with notes on how we do not know the best way to value the corporate, an identical subject that we had with Hire the Runway.
The next days and weeks are going to show illustrative when it comes to the worth of tech-enabled companies, particularly in distinction to extra digital and hard-tech efforts. But once more.
The fast-casual meals recreation
Sweetgreen operates its 140 meals spots in 13 U.S. states and Washington, D.C., with some 1.35 million clients inserting no less than one order within the 90 days concluding September 26, 2021. And for a know-how angle, some 68% of Sweetgreen income was generated from digital orders for its fiscal yr thus far, which ended September 26.
As famous above, workplace tradition has proved to be no small a part of Sweetgreen’s development. Per the corporate’s S-1 submitting, observe the way it discusses the influence of COVID-19 — which disrupted going to workplaces, interval — on its enterprise (emphasis: TechCrunch):
We skilled a decline in our In-Retailer Channel as a result of COVID-19 pandemic in fiscal yr 2020, significantly in central enterprise districts, which was partially offset by robust gross sales in our suburban places and robust off-premises digital gross sales throughout all markets. For our fiscal yr thus far by means of September 26, 2021, we skilled optimistic momentum throughout all of our channels, as COVID-19 vaccines grew to become extensively out there and clients began to return to workplaces.
Sweetgreen has persistently expanded throughout its life, noting in the identical submitting that it had “119 eating places as of the tip of fiscal yr 2020,” and 140 as of the tip of September of this yr. That development has not been cheap, with Sweetgreen “concentrating on” an “common funding of roughly $1.2 million per new restaurant” sooner or later.
Powering Sweetgreen within the background are just a few developments that the corporate views as accretive, together with a client shift towards extra plant-based consuming and “speedy adoption of digital and supply,” key channels for the meals chain’s income development.
No matter how you are feeling about Sweetgreen the model, the corporate’s total marketing strategy seems sound on paper. Persons are consuming more healthy and ordering extra by way of supply. Salads transport nicely — they don’t seem to be soup — and are as plant-based as you’d like. And since it’s potential to generate income promoting meals, why not Sweetgreen?
So, how has the corporate managed in enterprise phrases throughout its previous couple of years of development? Let’s have a look.
Does Sweetgreen’s enterprise generate candy quantities of inexperienced?
No, it doesn’t.
In reality, Sweetgreen is somewhat unprofitable and doesn’t seem like on the cusp of a speedy march towards profitability. Not that dropping cash is a sin, per se; many venture-backed firms run stiff deficits whereas they scale. That’s the level of elevating personal capital, to take a position it at the price of near-term profitability and money circulate.
However Sweetgreen is not any company baby. It was based in 2007, per Crunchbase information, making it almost sufficiently old to safe a learner’s allow to drive in the US. If a human can get to the purpose of nigh-maturity in a timeframe, absolutely firms made up of adults and backed by mountains of personal capital can handle the identical?
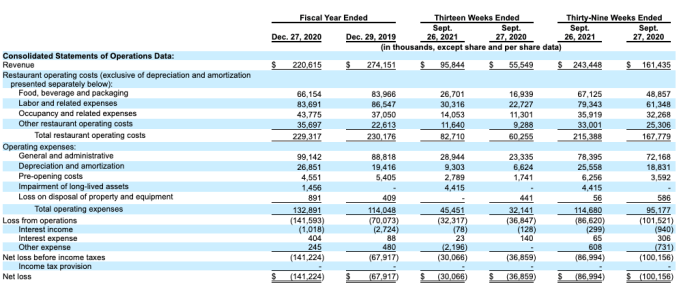
Right here’s the information:
Picture Credit: Sweetgreen S-1
Notice that point flows east to west on this specific desk, so the corporate’s most up-to-date full fiscal yr is on the far left.
As we will see from the 2 most up-to-date fiscal years, 2020 was a fairly arduous time for Sweetgreen, which noticed its revenues decline from $274.2 million to $220.6 million, and its web losses double from $67.9 million to $141.2 million over the identical timeframe.