

The second-quarter earnings season is effectively underway, offering a constructive counterpoint to a collection of gloomy information releases anticipated this week. To date, about 100 or extra of the S&P-listed firms have reported, and roughly 72% have been surprisingly on the upside. That is opposite to forecasts for later this week – market watchers anticipate the Federal Reserve to lift rates of interest by one other 0.75% on Wednesday, and anticipate Thursday’s announcement from the Bureau of Financial Evaluation to point out a second-quarter contraction, which might put the US right into a recession.
So what’s it? Are we earnings on the upside or are we firstly of a recession? It might rely on the Federal Reserve; because the central financial institution pushes up rates of interest to struggle inflation, the upper value of cash will put strain on the economic system, miserable each jobs and GDP development.
In a current observe to shoppers, Oppenheimer Chief Funding Strategist John Stoltzfus addresses these issues. He writes: “Our view stays constructive on the actions taken by the Federal Reserve to date because it pivoted within the fourth quarter of final 12 months. We consider that actions by the Fed resulting in what we name ‘the tip of ‘free cash’ is an efficient factor for buyers and the US economic system. An excessive amount of liquidity within the system fuels hypothesis, overinvestment and distortion of valuations and expectations.”
“In our view, thus far the Fed is doing the job that must be finished whereas displaying sensitivity to the short-term results on the economic system of its change in coverage. Progress not perfection stays the order of the day in our view,” Stoltzfus added.
With Stoltzfus’ outlook in thoughts, we took a better have a look at two shares that Oppenheimer helps. The agency’s analysts see at the very least 60% upside potential forward for every. We used TipRank’s platform to search out out what the remainder of the road has to say.
Peloton Interactive (PTON)
The primary Oppenheimer decide we’ll have a look at is Peloton, the interactive dwelling train firm that reimagined dwelling train, combining the venerable stationary bike with social media and digital video connections. The end result: the creation of an internet linked neighborhood, a characteristic that permits prospects to hitch group train courses from the consolation of their very own front room or basement. This connection, which drastically benefited Peloton through the pandemic disaster, stays an necessary promoting level for the corporate.
On the similar time, the financial reopening of the previous 12 months has in itself put strain on Peloton. As prospects bought out extra, there was much less want for at-home coaching choices, and Peloton’s monetary outcomes, which confirmed progress via the primary three quarters of fiscal 2021, have tightened. Income fell again from 3Q21’s peak of $1.26 billion and earnings have turned deeply unfavorable.
In the newest quarter, Q3 of fiscal 2022, the corporate posted $964.3 million on the highest line, down 23% year-over-year. Earnings, which registered a lack of 3 cents per inventory within the year-ago quarter, fell to a a lot deeper EPS lack of $2.27 — and worse, coming in under the forecast of $83 cents. Preserving this within the background, PTON’s share decline – about 73% year-to-date – makes higher sense.
On a constructive observe, the corporate has seen its complete membership enhance steadily in current quarters, from 5.4 million in fiscal 3Q21 to 7 million in fiscal 3Q22.
Oppenheimer 5-star analyst Brian Nagel, who holds the #34 spot within the TipRanks database, describes Peloton as ‘down however not out’.
Laying out this case, Nagel writes, “The previous a number of quarters have confirmed tumultuous for Peloton and its inventory because the story has shifted quickly from promising tech unicorn, to COVID-19 winner, to post-pandemic sufferer. Via lens of analysts with longstanding backgrounds in shopper and health, we fastidiously reexamined PTON and the corporate’s distinctive enterprise mannequin. Important challenges stay for Peloton. That stated, we consider that inside the dynamic and fragmented well being and wellness section is the chance for a greater managed and extra disciplined PTON. Our constructive name on PTON is long term and extremely speculative in nature.”
Befitting his optimism, Nagel charges PTON inventory as Outperform (i.e. Purchase), with a value of $20 implying a robust upside of 109% for the approaching 12 months. (To see Nagel’s observe file, click on right here)
The ‘long-term and extremely speculative’ nature of Peloton as an funding, in addition to its underlying energy, is obvious from the Wall Avenue consensus. The inventory has picked up 27 analyst opinions in current weeks and months, and these embody 14 buys, 11 holds and a couple of sells, for a reasonable purchase consensus ranking. Shares are buying and selling at $9.55 and their common goal of $21.04 suggests a one-year upside potential of 120%. (See Peloton inventory forecast on TipRanks)


XPO Logistics (XPO)
The opposite inventory on Oppenheimer’s radar is a trucking and transportation firm, XPO Logistics. This firm, based mostly in Connecticut, is a big operator within the subject of freight transportation and in addition acts as a freight dealer. On the core of the corporate’s enterprise is its less-than-truckload freight section, which operates globally – and in North America can attain 99% of all zip codes within the US in addition to vital areas in each Canada and Mexico.
XPO’s transport brokerage is on the middle of the corporate’s plans for effectivity; XPO will spin off this section as a separate public entity this 12 months. The brand new freight brokerage, which is able to conduct enterprise in a technology-enabled mannequin, will probably be referred to as RXO, whereas XPO will stay the moniker of the LTL and transportation section as a pure-play trucker. The separation is anticipated to be accomplished through the fourth quarter.
In the meantime, XPO is going through a number of headwinds which have put downward strain on shares. The price of diesel gasoline has risen by a whopping 76% previously 12 months, and that has buyers frightened. The inventory has fallen by 30 per cent.
On the similar time, XPO’s monetary outcomes have been wholesome. The corporate will report Q2 outcomes on August 4, however we are able to look again at Q1 to get a way of the place this logistics firm stands.
It stands on agency floor. The Q1 high line hit an organization file of $3.47 billion, up practically half a billion, or 16%, from the year-ago quarter. Diluted EPS additionally rose year-over-year, giving a acquire of 56 cents per share to succeed in $4.23.
For Oppenheimer’s Scott Schneeberger, one other of the agency’s 5-star analysts, all of this provides as much as a inventory that buyers ought to regulate.
“We see XPO and its entry level enticing forward of its 8/4/22 2Q22 earnings launch, the attainable sale/itemizing of its European transportation enterprise and its pending 4Q22 spin-off of RXO. We comfortably preserve our 2Q22E Adjusted EBITDA of $365M (+ 10% y/y; $360-370M steerage; $364M consensus) after business checks,” Schneeberger stated.
“We consider that XPO’s North American LTL profitability initiatives are on observe, whereas its North American truck brokerage enterprise, the cornerstone part of the pending RXO spin-off, has traditionally outperformed business tendencies. We view the prevailing stage of financial uncertainty as greater than totally embedded in XPO’s present valuation versus significant upside potential in executing on its strategic aims,” the analyst continued.
To that finish, Schneeberger charges XPO inventory an Outperform (i.e. Purchase), unsurprisingly in mild of his feedback, and units a value goal of $87, implying a strong 61% one-year upside for the inventory. (To see Schneeberger’s observe file, click on right here)
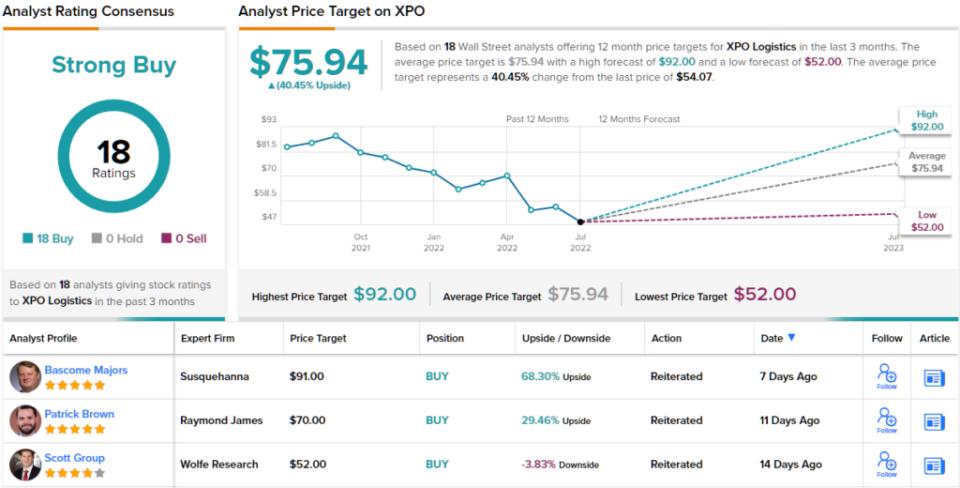
It’s not typically that the analysts all agree on a inventory, so when it does, concentrate. XPO’s Robust Purchase consensus ranking is predicated on a unanimous 18 Buys. The inventory’s common value goal of $75.94 suggests ~40% from the present share value of $54.07. (See XPO inventory forecast on TipRanks)

To search out nice inventory buying and selling concepts at enticing valuations, go to TipRanks’ Finest Shares to Purchase, a newly launched instrument that unifies all of TipRanks’ inventory insights.
Disclaimer: The opinions expressed on this article are solely these of the featured analysts. The content material is meant for use for informational functions solely. It is extremely necessary to do your personal evaluation earlier than making any funding.