Why MSMEs are shunning credit score assure plan
Capital Markets
Why MSMEs are shunning credit score assure plan
Tuesday February 14 2023

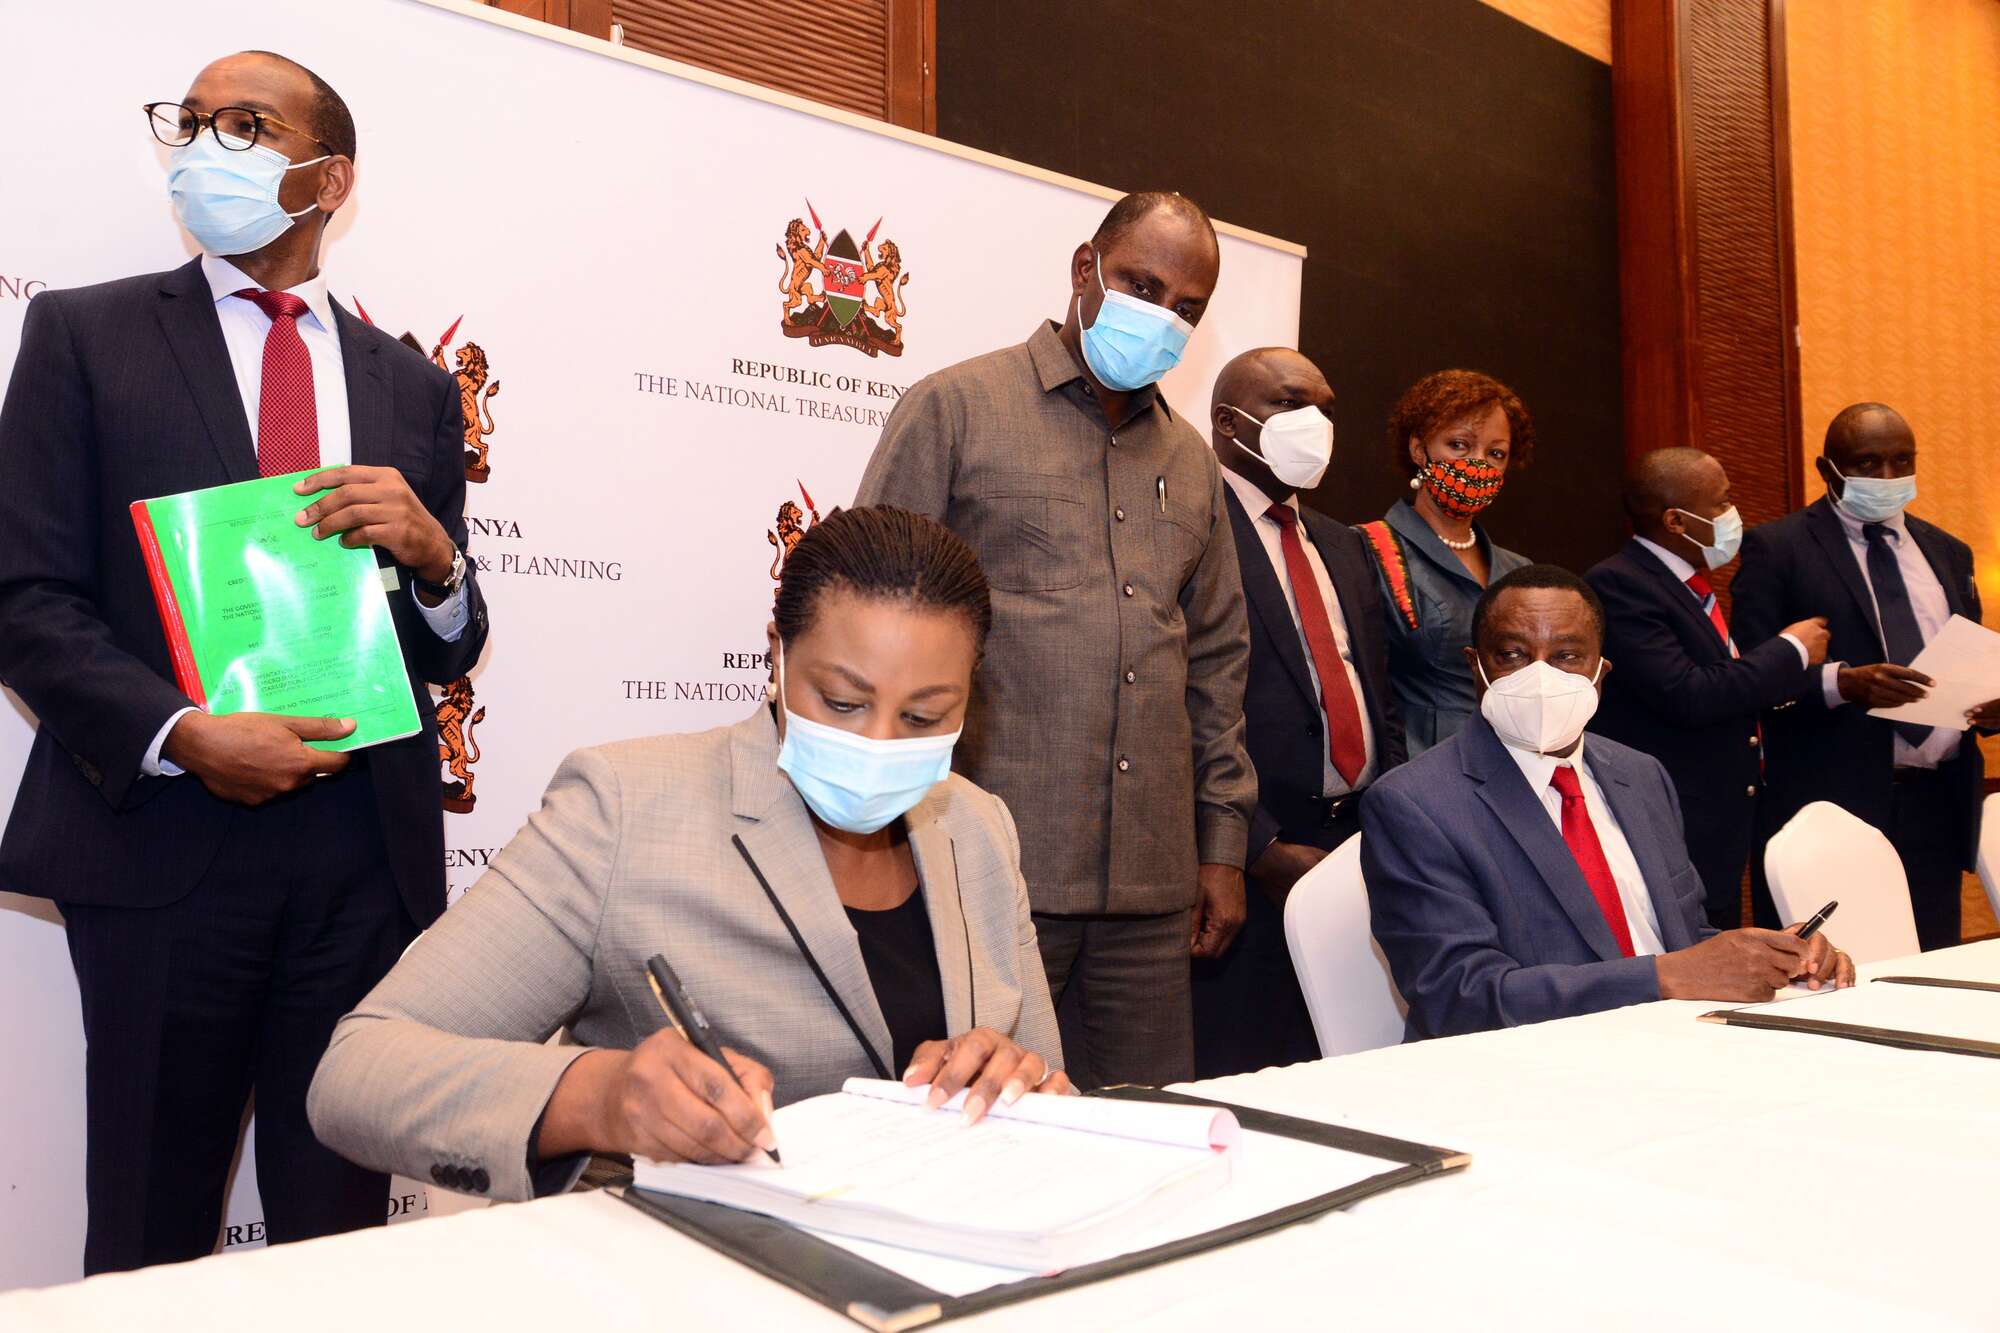
Credit score Financial institution CEO Betty Korir indicators the Credit score Assure Scheme Settlement with the Treasury in Nairobi on December 8, 2020. FILE PHOTO | NMG
When it was launched in December 2020, the Treasury’s credit score assure scheme for micro, small and medium-sized enterprises (MSMEs) was meant to open up entry to financial institution loans for the sector that has struggled to draw credit score because of threat issues.
By the tip of final yr, disclosures by the Central Financial institution of Kenya (CBK) present, MSMEs had taken up a cumulative Sh4.4 billion in loans below the scheme from the seven taking part lenders—Absa, Credit score Financial institution, KCB Group, NCBA, Diamond Belief Financial institution, Stanbic Financial institution and Cooperative Financial institution.
Which means the lenders have solely accessed about Sh1.1 billion value of ensures out of the preliminary Sh3 billion put aside by the Treasury for the scheme.
The federal government provides cowl for 1 / 4 of the principal lent to the small companies, that means that the Sh3 billion seed fund must unlock lending value not less than Sh12 billion. The utmost mortgage restrict is ready at Sh5 million per borrower, with a compensation interval of 36 months.
MSMEs’ wrestle to entry credit score was amplified by the Covid-19 pandemic that harm enterprise efficiency. The expectations of a loosening of purse strings for them have, nevertheless, not materialised, not less than to not the extent that the planners of the assure scheme anticipated.
Numerous small enterprises, particularly people who have tried and did not get loans from banks beforehand, have most popular to proceed accessing funding from non-bank actors comparable to saccos with whom they’ve constructed relationships that enable them to get cash at moderately decrease charges in comparison with financial institution loans.
The Treasury’s most up-to-date report on the scheme protecting the 2021/2022 fiscal yr, tabled in Parliament in November, recognized a number of different challenges affecting the uptake of the fund.
These embrace the unclear classification of companies throughout the definition of MSME below the Public Finance Administration Act and MSE Act of 2012, which in the end determines the quantity they will entry from the fund. As an illustration, the Treasury famous, a enterprise may qualify to be labeled as a micro-enterprise by the variety of workers on its books, whereas on foundation of turnover, it will fall below the definition of a small or medium enterprise.
On the financial institution’s facet, there’s additionally the danger of misclassification of MSMEs below the broad financial sectors that banks use to outline debtors. As an illustration, the Treasury mentioned, some enterprises in training, agriculture and healthcare find yourself being labeled as commerce enterprises, and will, as an example, be denied loans based mostly on money stream tendencies that differ from these anticipated of a buying and selling firm.
A lot of the small companies are additionally not tax-compliant, which locks them out from accessing the fund. Some due to this fact want to supply capital elsewhere, afraid of hefty tax arrears calls for in the event that they have been to formalise with a view to qualify for the ensures.
The Treasury additionally highlighted an imbalance within the distribution of funds favouring giant city centres, primarily because of the bigger presence of the taking part banks in these areas in comparison with far-flung counties.
Nairobi County, as an example, took up 52 % or Sh1.73 billion out of the Sh3.3 billion that had been disbursed to MSMEs below the scheme by June 2022.
Kiambu, Mombasa, Kisumu and Nakuru, which comply with Nairobi when it comes to the city inhabitants, collectively accounted for an additional 20 % or Sh656 million value of the disbursed loans. In the meantime, Wajir, Mandera and Marsabit did not register any loans within the interval, owing to a scarcity of presence of the taking part banks, and likewise the restricted variety of MSMEs in these areas.
One other issue has been the deteriorating high quality of the banking sector mortgage guide, the place non-performing loans stay elevated even because the economic system continues to recuperate from the lows of 2020.
On the finish of final yr, the ratio of gross NPLs to mortgage guide for the banking sector stood at 13.3 %, forcing banks to keep up or tighten credit score requirements throughout many lending sectors.
The answer, in response to the Treasury, lies in onboarding a bigger variety of monetary intermediaries into the scheme with a view to widen the geographical attain of the fund.
In a few of the predominantly rural counties, microfinance establishments and Saccos have a far wider attain in comparison with industrial banks.
→ [email protected]